
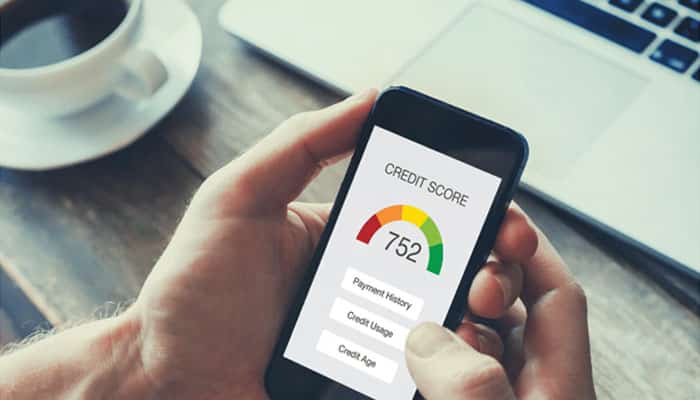

Reaching the 800 credit score tier is often an engineering challenge that requires three specific inputs: age, limit, and perfect payment history. For borrowers with clean but thin files, a strategic Coast Tradelines tradeline sale adds the depth needed to qualify for prime lending rates in weeks, not years. By leveraging a seasoned authorized user account, you can optimize the most influential factors in your credit report to secure better terms on mortgages and auto loans.
Beyond the Basics: What a Tradeline Actually Does for Your Report
A thin file punishes you twice. Lenders see no track record, so they price you like a risk, and the only cure the traditional system offers is time you don’t have when a closing date is six weeks away. Strategic tradeline acquisition compresses that timeline by transferring existing account history onto your report instead of asking you to build it from scratch. It is the only legitimate way to add depth to a credit file in weeks rather than years.
Technically, a tradeline is any account listed on your credit report — a card, an auto loan, a mortgage. The key distinction here is the authorized user (AU) tradeline. When a primary cardholder adds you as an authorized user on a seasoned account, the bank reports that account to the bureaus under your name, and you inherit its opening date, payment history, and credit limit.
That inherited age feeds directly into the Length of Credit History factor, which accounts for approximately 15% of a FICO Score, including the age of your oldest account and the average age of all accounts. The market has scale behind it, too: TransUnion recorded 20 million year-over-year growth in bankcard tradelines as of Q1 2024. When you buy authorized user tradelines, you are operating inside a mature, high-volume reporting system.
The 30-Day Sprint: How Fast Will a Tradeline Boost Your Credit?
Most tradelines appear on a credit report within 15 to 45 days, because posting is tied to the primary account’s statement cycle rather than the date you paid. The bank adds you as an authorized user, the account closes its billing period, and the AU data flows to the bureaus in that month’s reporting file. Miss the cutoff by two days, and you wait another full cycle.
This is where a compressed 7-day reporting window changes the math. Accounts selected specifically for an imminent statement date can post inside a single week, which is the difference between qualifying for a rate lock and watching it expire.
The directional evidence on file depth is encouraging. Experian found that 70% of unscored borrowers with a CBA tradeline reached prime or near-prime status within one year — a reminder that the jump from invisible to bankable is often about data, not decades.
Be realistic about starting points. A file in the 500s carrying active delinquencies has structural problems a single account will not resolve. A clean but thin file sitting in the 600s is the profile where the fastest movement toward 700 typically happens.
Best Practice or Fake Shortcut? Navigating the Ethics of Tradeline Sales
The “shortcut” label gets applied indiscriminately, so separate two very different activities. Credit repair fraud means disputing accurate information, buying a CPN, or fabricating a synthetic identity — all of it illegal, all of it eventually unwound by the bureaus. Adding an authorized user to a credit card is a feature banks built, document, and advertise. Parents do it for teenagers. Spouses do it for each other. Nothing about the mechanism changes when the primary cardholder is compensated. In fact, the FICO 8 scoring model—the version most lenders use—still includes authorized-user tradelines in its calculations to ensure score accuracy.
That is the entire premise of piggybacking: issuers report AU accounts because federal regulation requires equal reporting treatment, and scoring models read that data as legitimate history. A tradeline sale is a rental of reporting access, not a manipulation of the record.
What has changed is where growth comes from. The CFPB documented a 33% decline in total collections tradelines from 2018 to 2022, meaning fewer files are being dragged down by third-party debt and more scoring separation now comes from the positive side of the ledger. Building affirmative history is the lever with the most room left.
None of this erases a valid bankruptcy, charge-off, or late payment. Those age off on their own schedule.
The Roadmap to 800: Selecting High-Limit and Seasoned Accounts
Not every account moves the needle. Three variables do the work.
Age. “Seasoned” means real history — accounts opened five, ten, or more years ago. An eighteen-month-old card adds almost nothing to your average account age. A decade-old card repositions your entire Length of Credit History profile in one posting cycle.
Limit. This is the utilization buffer. If your own cards carry balances pressed against low limits, adding a single account with a limit in the tens of thousands of dollars drops your aggregate debt-to-limit ratio immediately, because the denominator expands while your balances stay put. Utilization is recalculated every cycle, which is why this factor moves fastest.
Fit. Diagnose before you buy. A file with three young cards and no derogatories needs age. A file with solid history and maxed cards needs limit. Buying the wrong variable wastes the money and the cycle.
Better scores also buy better pricing, and lending volume is there to compete for: the NCUA reported 4.6% growth in total loans outstanding at federally insured credit unions for the year ending Q1 2024. Credit unions price aggressively for strong tiers.
Tradeline Variable Comparison
| Variable | Primary Benefit | Best For | Impact Speed |
| Account Age | Increases Length of Credit History | Thin files with young accounts | 15-45 Days |
| Credit Limit | Lowers Credit Utilization Ratio | Files with high balances/maxed cards | 15-45 Days |
| Payment History | Establishes reliability | Unscored or ‘Credit Invisible’ files | 15-45 Days |
Strategic Filtering: How to Shop the Tradeline Marketplace
Treat the marketplace like a screening tool, not a catalog. Filter first by age, since that is the variable you cannot manufacture any other way. Then filter by limit against your current balances. Finally, and most people skip this, filter by statement date. The statement date determines when the account reports, so if your loan officer pulls credit on the 20th, you need an account that closes its cycle well before that — not one that posts the following month.
Insist on guaranteed posting to all three bureaus. Mortgage and auto underwriting frequently pulls a tri-merge report, and an account that only surfaces on one bureau may never reach the score the lender actually uses. A written posting guarantee with a refund provision is the baseline standard before you purchase tradeline inventory.
Brokers managing multiple client files should look for VIP or professional programs that open bulk inventory, reserved slots, and advance visibility into upcoming statement dates. Volume access is what makes tradeline sales workable as a repeatable service line rather than a one-off favor.
Skip any account showing a recent late payment, no matter how attractive the limit. You inherit the blemish along with the history.
The Bottom Line: What You Need to Know About Tradeline Growth
- Authorized user tradelines are the fastest available way to add both Length of Credit History and credit utilization depth to a file, because you inherit an existing account’s age and limit rather than building them over years.
- Expect a reporting window of roughly 7 to 30 days, driven entirely by the primary account’s statement date rather than your purchase date.
- Adding the right tradelines can provide the quick credit score glow-up needed for major loan approvals.
- A single high-limit, seasoned account can separate a mid-600s file from the 720-plus tier where lenders price their best terms, though the outcome depends on what else is already on your report.
- Always confirm the marketplace guarantees posting to all three bureaus and backs it with a money-back policy.
The strategy is simple to state and easy to execute badly: diagnose which scoring factor is holding your file back, buy the account that fixes that specific gap, and time the posting to land before the lender pulls your credit. Keep your own accounts current while the tradeline does its work, because inherited history supplements good behavior — it does not substitute for it.
Securing Your Financial Future with Coast Tradelines
An 800 score is an engineering problem with known inputs. You need age, you need available limit, and you need both of them reported before your lender pulls the file. Coast Tradelines was built around exactly those inputs, specializing in high-limit, aged accounts with verified payment histories and clearly published statement dates so you can time the boost instead of hoping for it.
If your closing date is close, the 7-day reporting window is the difference between submitting a stronger file and submitting the one that already got declined. Browse inventory by age, limit, and posting date, choose the account that addresses your actual weak spot, and let the cycle do the rest.
Brokers and credit consultants should look at the VIP program, which opens bulk inventory and priority placement for professionals managing several client files at once — the practical infrastructure for turning score improvement into a service you can deliver on a schedule.
Waiting another five years for your average account age to mature is a choice, not a requirement. Start building your file at Coast Tradelines and put a real timeline on the score you need.
Key Tradeline Definitions
Tradeline: Any account that appears on a credit report, such as a credit card, mortgage, or auto loan.
Authorized User (AU): A person added to a credit card account by the primary owner, allowing the account’s history to be reported on the AU’s credit file.
Seasoned Tradeline: An account with a long, established history of on-time payments, typically several years old, used to increase the average age of a credit file.
Statement Date: The date a lender closes a billing cycle and typically reports account data to the three major credit bureaus.
Most major credit card issuers report authorized user activity to at least one of the three major credit bureaus (Equifax, Experian, and TransUnion), though the specific reporting practices vary by financial institution. This mechanism allows that history to appear on your personal report.
Frequently Asked Questions About Tradeline Sales
Can you legally buy a tradeline?
Yes. The practice of ‘piggybacking’ credit—becoming an authorized user to improve a score—is a long-standing practice that lenders and credit scoring models like FICO have historically permitted and recognized as legitimate.
What are tradeline sales?
A tradeline sale is a transaction where a primary cardholder with a seasoned, high-limit account adds a third party as an authorized user for a fee. This lets the buyer inherit the account’s positive history on their credit report.
Is buying a tradeline worth it? For borrowers with ‘thin’ credit files (fewer than five tradelines), purchasing a seasoned account can be the most efficient way to reach the 760+ tier required for prime interest rates, potentially saving thousands in interest over the life of a loan.
How much does it cost to buy a tradeline?
Costs vary based on the account’s age and credit limit. Generally, the older the account and the higher the limit, the higher the price, reflecting its greater impact on the buyer’s credit score.
Sources & References
To ensure transparency and EEAT (Experience, Expertise, Authoritativeness, and Trustworthiness), this article relies on the following primary sources and industry reports:
- FICO Score Factors: What’s in My FICO Score? (myFICO)
- Credit Market Trends: Q1 2024 Credit Industry Insights Report (TransUnion)
- Credit Building Analysis: Experian Analysis Shows CBA Tradelines Help 70% of Unscored Borrowers (Experian)
- Regulatory Guidance & Scoring: Fair Lending Guide – Regulation B and FICO Models (Federal Reserve)
- Debt Collection Trends: Market Snapshot: Trends in Third-Party Debt Collections Tradelines Reporting (CFPB)
- Credit Union Growth: Quarterly Data Summary – First Quarter 2024 (NCUA)
